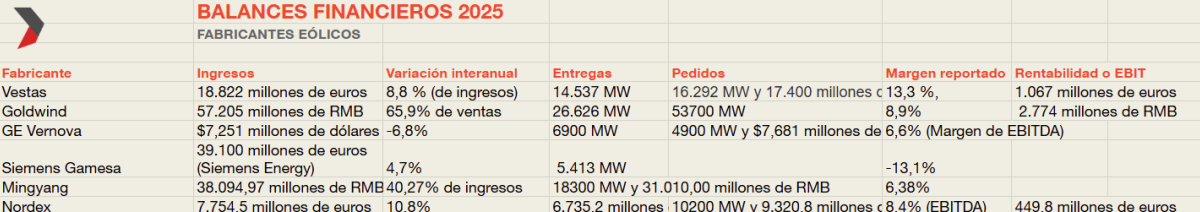
The wind energy industry closed 2025 with a record number of global installations, but market growth did not translate uniformly to the balance sheets of the leading wind turbine manufacturers . A survey conducted by Energía Estratégica on the annual results of the leading companies shows that Nordex, Vestas, Goldwind, and Mingyang returned to profitability, while GE Vernova and Siemens Gamesa continue to operate under significant financial pressure.
The biggest surprise was Nordex , which doubled its EBITDA, multiplied its net profit, and exceeded its profitability targets ahead of schedule. Vestas also achieved its best margin since 2019, although the deployment of its offshore platform is still incurring high costs.
In China, Goldwind and Mingyang Smart Energy benefited from increased deliveries, sales of higher-capacity turbines, and a gradual stabilization of prices . Both companies increased their revenue and improved their manufacturing margins.
The situation is different for GE Vernova and Siemens Gamesa. The wind power division remains GE Vernova's only loss-making unit , while the Siemens Energy subsidiary continues to post double-digit losses, although it expects to reach financial equilibrium during fiscal year 2026.

It is worth remembering that the industry installed 165 GW of new wind power during 2025, 40% more than in the previous year , and brought the cumulative global capacity to approximately 1,299 GW.
Asia accounted for nearly 80% of the new capacity additions, with 131 GW , driven primarily by China and India. China added over 120 GW and India reached a yearly high of 6.3 GW, while Europe surpassed 300 GW cumulatively after adding 19.1 GW.
“The strong increase in global wind installations sets a new standard for an industry that is rapidly accelerating,” says Ben Backwell, CEO of the Global Wind Energy Council .
The advantage of Chinese suppliers also deepened. Eight of the top ten manufacturers by sales volume are from China , a dominance supported by the size of its domestic market, integrated industrial chains, and more powerful equipment.
Nordex and Vestas lead the western recovery
Among the companies analyzed, Nordex showed the most significant financial leap . Its sales increased by 3.5%, to €7,553.5 million, but its profits grew well above revenue.
EBITDA reached €631 million , compared to €296.4 million in 2014, and the margin improved from 4.1% to 8.4%. Net profit rose from just €8.8 million to €274.3 million.
The company attributed the improvement to a better project mix, lower raw material and logistics costs, and more efficient execution. Gross margin rose from 21% to 27%, while Services achieved an EBIT margin of 18.1%.
Nordex also posted record free cash flow of €863.3 million. Order intake reached 10.2 GW, up 22.5%, and the total order backlog reached a record €16,093.6 million. With these results, the company raised its medium-term EBITDA margin target to 10%-12%.
On the other hand, Vestas also consolidated its recovery , with record revenues of €18.822 billion, up 8.8%. During the year, it delivered 14,537 MW, of which 12,560 MW corresponded to onshore projects and 1,977 MW to offshore installations.
“Vestas achieved its highest historical revenues and profitability at the upper end of its forecasts,” says Henrik Andersen, CEO of the company .
The EBIT margin before special items reached 5.7% , its best performance since 2019. EBIT increased from 741 million to 1,067 million euros and net profit advanced from 494 million to 780 million.
The Services division continued to be the most profitable, with an EBIT margin of 16.6%, while Power Solutions reached 5.4%.
The combined order book for turbines and services reached a record €71.9 billion . However, Offshore continues to face pressure from industrial commissioning costs, amortization, and bottlenecks related to the V236-15.0 MW turbine.
Vestas forecasts revenues of between 20 billion and 22 billion euros and an EBIT margin of 6%-8% by 2026.
Goldwind and Mingyang regain market share in China
Goldwind combined volume growth with improved profitability . Its revenue reached 73.023 billion yuan, up from 56.699 billion in 2024.
Continue reading
The manufacture and sale of wind turbines generated 57.205 billion yuan, while the capacity sold to external customers increased by 65.9%, to 26,626 MW .
Over 70% of sales were for turbines between 6 MW and 10 MW. This focus on higher-power equipment helped the industrial business margin increase from 4.9% to 8.9% .
Net profit attributable to shareholders increased from 1.86 billion to 2.774 billion yuan , while return on equity advanced from 4.91% to 7.08%.
The order backlog reached 53.7 GW , including 9.27 GW internationally. Goldwind thus managed to offset the low prices in the Chinese market through economies of scale, higher power per unit, and overseas expansion.
Mingyang Smart Energy showed a similar, though less uniform, recovery . Its revenue grew by 40.27% to 38,094.97 million yuan.
The sale of wind turbines and accessories generated 31.01 billion and deliveries reached 18.3 GW , with 16.1 GW onshore and 2.2 GW offshore.
The gross margin for the turbine business reached 6.38%, an improvement of 6.84 percentage points. Profit attributable to shareholders increased by 90.65% to 659.87 million yuan .
However, other segments remained under pressure. The margin for energy station products fell by 14.18 percentage points, and the power generation business saw its revenue decline by 21.73%.
The other businesses, including photovoltaic products, closed with a negative margin of 0.70%. Therefore, Mingyang is recovering profitability in manufacturing, but still faces contractions in its complementary energy activities .
GE Vernova and Siemens Gamesa are still in the red.
GE Vernova 's wind division reported revenues of $9.11 billion, a 6% organic decline. Onshore Wind contributed $8.241 billion, Offshore Wind $652 million, and LM Wind Power $217 million.
Orders grew 8% to $7.681 billion, but the backlog fell 5% to $21.630 billion. The segment posted a negative EBITDA of $598 million and a margin of -6.6%. Onshore improved thanks to higher prices and deliveries, but Offshore recognized additional losses on contracts of $637 million.
The main impacts came from changes in schedules, supply cost overruns and work to correct quality issues, including the recall of blades at Vineyard Wind.
However, Wind remains the group's only loss-making division. Onshore improvements have not yet offset losses from inherited offshore contracts .
Siemens Gamesa also remains in negative territory. The Siemens Energy subsidiary increased its revenue by 4.7%, but closed with a margin before special items of -13.1% , the worst percentage indicator in the survey.
In 2025, the company supplied 5,413 MW. “At Siemens Gamesa, we continue working on measures to reach the break-even point in 2026,” they stated.
Management prioritizes contracts with better conditions, although this greater commercial selectivity may temporarily limit the inflow of orders.
The survey confirms that selling more MW does not guarantee greater profitability . Contract quality, price discipline, services, and offshore exposure are key factors.
Thus, 2025 marked the beginning of a new stage: onshore wind power is recovering margins, but offshore wind continues to concentrate the main financial risks of the industry .