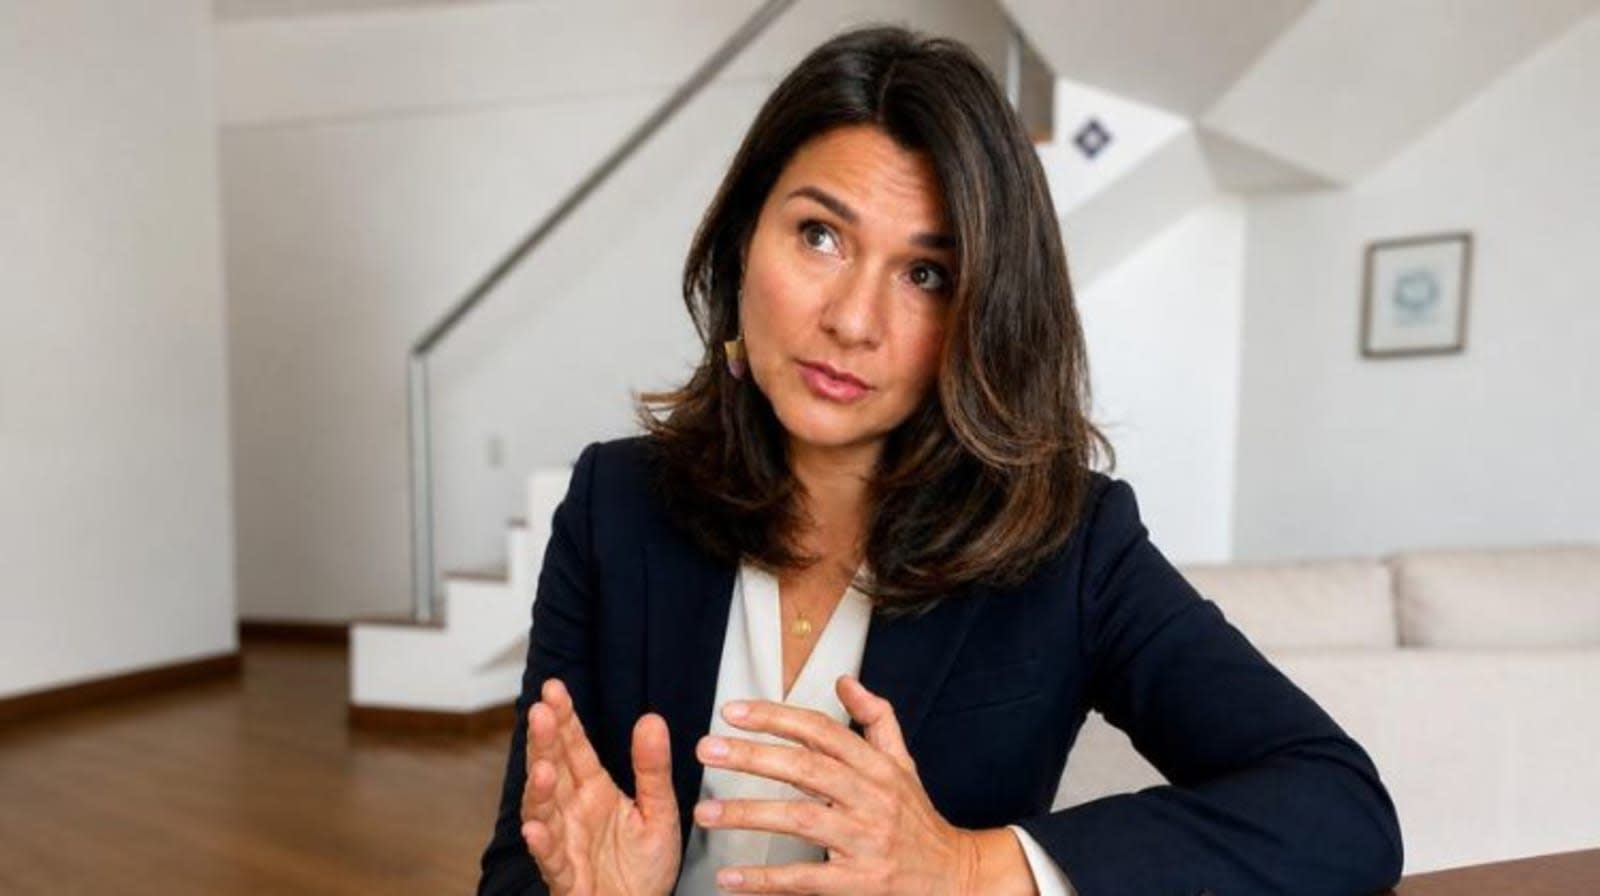
Peru's electricity market may have to wait until the end of 2027 for renewable energy tenders, even if the Ministry of Energy and Mines (MINEM) fulfills its commitment to approve the pending regulations before December of this year .
This is the opinion of Raquel Carrero , a specialist in renewable energies, who questions the content of the regulatory proposals and warns that the proposed provisions do not guarantee conditions to finance new generation plants.
“It’s good that the minister has set a date, but what’s important is the content, and what we’ve seen so far, in my opinion, won’t bring good signals for new investments in power generation plants,” Carrero said in an interview with Energía Estratégica .
The warning comes as the Peruvian government moves forward with the regulation of Law No. 32249, which modifies Law No. 28832 , to transform the mechanisms of electricity contracting through differentiated purchases of energy and power, time blocks and long-term contracts.

The project includes supply agreements of 10 to 15 years, intended to provide predictability for market participants. However, the debate centers on whether the design will be exclusively for new power plants or whether they will compete with existing ones.
“The long-term purchase of energy for the regulated market is a mechanism designed to incentivize the construction of new generation plants, but the ministry is not regulating it to fulfill that objective,” the executive questioned.
In this regard, the specialist argues that contracts must become effective instruments to support financing, with terms in line with investment cycles, transparent competition, and an adequate distribution of risks.
The concern also extends to the regulations for complementary services, whose design should allow different technologies to compete to offer frequency regulation, reservations and other services necessary for the stability of the system.
Carrero believes that the current proposals do not sufficiently develop essential aspects and leave relevant decisions subject to subsequent procedures, making it difficult to anticipate the conditions for participation.
“Legal certainty does not depend solely on publishing regulations, but on these regulations being complete, predictable and sufficiently stable to encourage long-term investment,” he stressed.
Why might the bidding process only take place at the end of 2027?
Although the Ministry of Energy and Mines (MINEM) aims to complete the regulations before the end of 2026, the publication of the rules would not imply an immediate call for applications .
Carrero explains that subsequently the procedures of the Supervisory Body for Investment in Energy and Mining (Osinergmin) must be adapted, the bases of the competitions must be defined and the contracting requirements of the distributors must be established.
These administrative and technical processes would take several months before the first awards could be made.
Added to this is a commercial constraint: the actual availability of demand to contract new generation .
For years, distribution companies met some of their needs through bilateral agreements, rather than holding public tenders. Therefore, it will be necessary to determine what supply volumes can be committed to in future processes.
Under these conditions, Carrero estimates that the calls for bids “could take place at the end of 2027” , a projection that highlights the gap between regulatory approval and the effective opening of the market to new investments.
However, for the specialist, the challenge is not solely about accelerating the processes, but about ensuring that the contracting drives additional infrastructure and allows different technologies to compete.
New power plants versus existing generation: the critical point of the regulation
One of Carrero's main concerns focuses on the possibility that currently operating power plants can compete against new projects in long-term tenders , without distinguishing their investment conditions.
The specialist warns that existing facilities do not face development risks and may have recovered a considerable portion of their capital, while new ventures must secure financing, permits, and build infrastructure before they can begin generating revenue.
Therefore, it rejects the idea that both types of projects should compete for the same contracts when the objective of the call is to incorporate additional capacity.
“It is probably one of the most important aspects that should be corrected because Law 32249 seeks to ensure the efficient, reliable and competitive supply of the electrical system,” she says when asked about the joint participation of new and operational power plants.
This does not imply excluding existing facilities from the market, but rather differentiating the contracting objectives : reserving the processes aimed at expanding the generating fleet for new investments and allowing operational assets to meet short and medium-term needs.
Continue reading
This position also finds support among developers in the Peruvian market. Guillermo Grande, CEO of EDF Peru , stated during the Future Energy Summit Peru 2026: “Long-term tenders need to be reserved exclusively for new projects.”
The executive branch proposes that operating power plants participate in shorter bidding processes. Meanwhile, EDF Peru is requesting pre-operational studies, environmental certification, and progress reports on concessions, while Ignis Energy Peru proposes prioritizing new infrastructure to ensure its bankability.
For its part, ENGIE requests objective qualification criteria and the possibility of admitting projects that already have authorization or concessions. However, the company, along with Kallpa and Statkraft, also advocates for the participation of existing power plants in the competitive bidding processes.
Another aspect questioned by Carrero is the implementation of time blocks, one of the central tools of the reform to separate the contracting of energy and power and incorporate new technologies.
The specialist believes that the drafts still show resistance to modifying the current system and warns that hiring should not reproduce the conditions that the reform seeks to overcome .
“Clearly there is a resistance to change, which is natural, but that should not be a justification for not making changes,” he points out.
It also proposes reviewing the treatment of variable power under previous contracts. According to the report, the proposed regulations intend to treat it as fixed, a decision that requires verifying that the original conditions are respected without expanding the economic rights of the suppliers.
That interpretation could modify the amount of demand available to new participants , conditioning hiring opportunities.
It also questions the exception that would allow distributors to contract their own generation without bidding until the publication of the distributed generation regulations, a provision that has been pending for more than a decade.
According to Carrero, a temporary measure should have a verifiable expiration date and not be subject to the approval of another regulation without a certain date.
Hydroelectric plants under scrutiny and projects seeking financing
The regulatory discussion extends to the Peruvian government's bid to reactivate hydroelectric tenders , a strategy that Carrero questions in light of the competitiveness of solar and wind technologies.
The Ministry of Energy and Mines (MINEM) is analyzing contracting mechanisms with guaranteed rates and contracts of up to 20 years to incentivize new hydroelectric plants, given the system's capacity needs.
The initiative gains relevance in light of the projections included in the 2027-2036 Transmission Plan , which anticipate a possible efficient reserve deficit of 150 MW in 2027, 500 MW in 2028 and 800 MW in 2029 , if sufficient generation is not incorporated.
However, Carrero argues that hydroelectric plants face difficulties competing on price and investment costs against non-conventional renewable energy alternatives. Furthermore, he warns that these projects can take up to eight years to build and may face social conflicts related to water use.
The specialist believes it is necessary to justify why processes exclusive to this technology would be prioritized, instead of enabling open tenders that also allow renewable projects with batteries to compete .
It also proposes reviewing the regulatory benefits of hydroelectric plants, including the discount factor incorporated when non-conventional renewable sources had a lower level of technological development.
The debate also extends to Peru's competitiveness in attracting capital , in a scenario where regulatory uncertainty is leading developers to prioritize other Latin American markets.
“The truth is that several companies that were interested have decided to focus their efforts on other countries, because Peru continues to discuss how to regulate its electricity market, while other countries in the region have made progress not only in contracting renewable energy, but also in storage and flexibility mechanisms. We are lagging behind,” warns Carrero.
The size of the renewable energy portfolio contrasts sharply with the projected capacity additions. According to figures shared by César Butrón, president of the board of the Economic Operation Committee of the National Interconnected System (COES) , Peru has 29,000 MW of renewable energy projects undergoing environmental permitting , of which 5,831 MW have received final concessions .
However, the agency's implementation scenario towards 2030 contemplates approximately between 3,000 and 3,500 MW of new capacity , a difference that highlights the need to distinguish between projects under development and those with concrete prospects of materialization.
In this context, Carrero argues that the existence of a large solar and wind portfolio does not guarantee new investments , since it is essential to identify the developments that can actually access financing and begin their construction.
It also identifies supply restrictions in the north of the country and in regions such as Loreto, where dependence on diesel generation makes supply more expensive and limits the possibilities of industrial expansion.
“2027 should be the year that Peru moves from scattered announcements to the real creation of concrete conditions that attract new investment,” Carrero concluded.
 By Emilia Lardizabal
 By Energía Estratégica
 By Matías Medinilla