


The UK faces a crucial stage in transforming its early advantage in floating offshore wind into a globally competitive industry. With around 14% of the global portfolio, maintaining that position will depend on the speed of deployment over the next five years and the signals set by the first Strategic Spatial Energy Plan (SSEP).
The planning must provide sufficient visibility to enable developers, investors, and suppliers to maintain their commitments as the first commercial projects progress in Scotland and the Celtic Sea . The challenge will be to convert the existing pipeline into built parks, operational learning, and industrial scale before other markets absorb those capabilities.
Becky Fowell, Project Manager at Regen , described the first SSEP as a “critical test” of Britain’s long-term commitment to the technology. The document will define where future generation will be located and what volume will be needed to support a secure, affordable, and decarbonized electricity system by 2050.
The proposal comes as the British government maintains offshore wind as one of the pillars of Clean Power 2030 , with a target of between 43 and 50 GW of offshore wind capacity by the end of the decade , along with 27-29 GW of onshore wind and 45-47 GW of solar.

By the beginning of 2025, the UK already had 30.7 GW of offshore wind installed or committed and another 7.2 GW authorized. Reaching the target will require accelerating the transition from development and contract award to the construction, connection, and effective operation of the assets.
For floating technology, Regen identified a particularly narrow window. The next five years will be critical , coinciding with the delivery of the first larger-scale commercial deployments in Scotland and the Celtic Sea. Fowell stressed the need to “maintain the pace of deployment” to reduce costs, strengthen suppliers, and build industrial capacity.
The British market starts from a relevant position: Regen positioned the country with the third largest operating capacity of floating offshore wind in the world and approximately 14% of the global portfolio, backed by decades of offshore experience, capabilities developed in deep waters of the North Sea and accumulated knowledge in fixed-foundation offshore wind.
Scotland led the way in the early stages with some of the world's pioneering floating projects. The expansion into the Celtic Sea now opens up the possibility of extending this activity to other British regions and generating demand for ports, manufacturing, engineering, and maritime services. 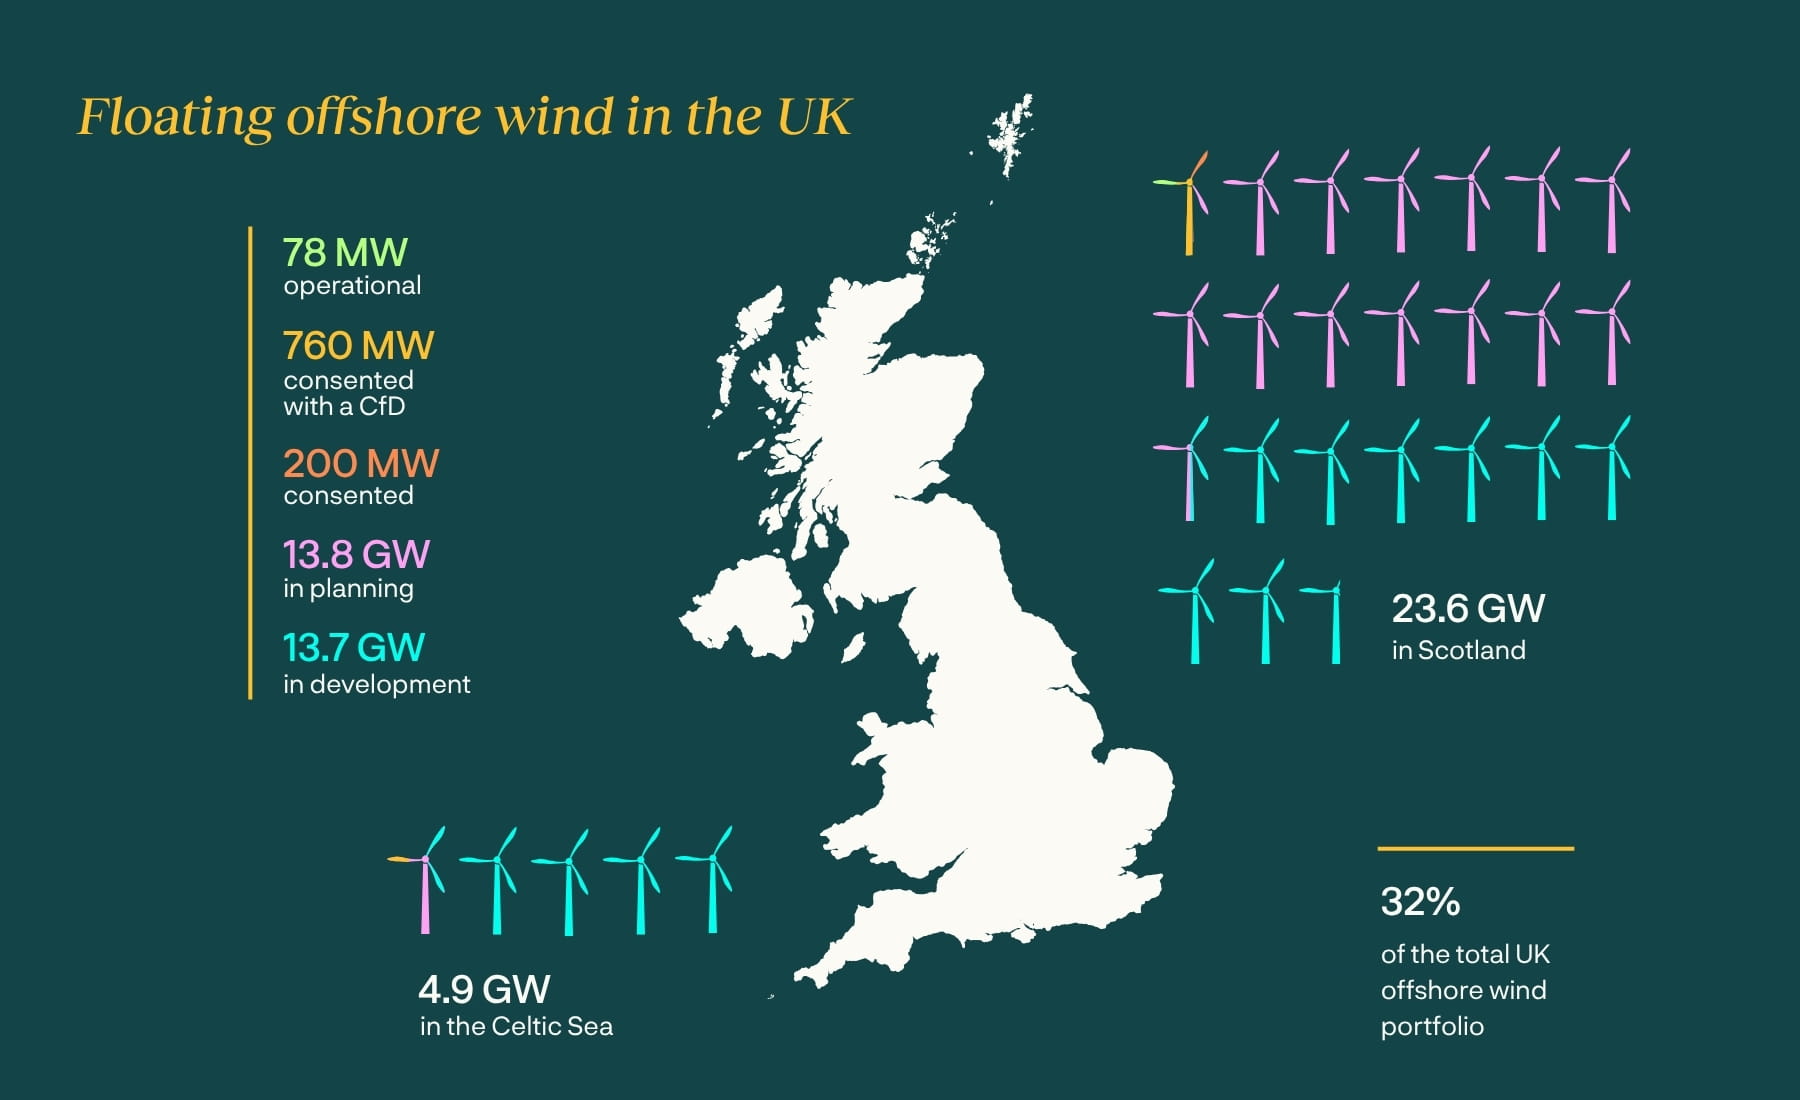
£25.5 billion committed and an industry that needs projects
The industrial scale of this undertaking is already mobilizing significant figures. Through ScotWind's Supply Chain Development Statements, developers have committed £25.5 billion to fixed-foundation and floating offshore wind projects.
The Clean Industry Bonus of Allocation Round 7 also mobilized approximately £3.4 billion of private investment towards British manufacturing, factories and ports and supports around 7,000 jobs , according to data collected by Regen.
Great British Energy, the National Wealth Fund, and other public bodies also committed up to an additional £1 billion to strengthen the offshore wind supply chain. Market continuity will be crucial for factories, ports, and suppliers to find sufficient future demand to support new investment decisions.
In response to this need, Fowell called for a “clear long-term deployment trajectory” that complements current commitments with a sufficiently deep vision for new developments. This certainty will be necessary both to sustain existing projects and to attract additional capital.
Cost reduction is another key component of the commercialization process. To scale up, the industry will need to accumulate construction and operational experience, optimize processes, and generate the volume that suppliers require to increase production capacity.
Following this logic, waiting for a price drop before deploying more capacity could hinder the very process needed to achieve it . Fowell summarized the argument by pointing out that reductions must be achieved “not by waiting for deployment to happen,” directly linking the continuity of the portfolio to the industrial learning curve.
Regen also argued that the SSEP should not evaluate floating offshore wind solely using the levelized cost of energy (LCOE) . The technology allows access to deeper waters with intense and geographically diverse wind resources, complementing other generation sources and contributing to the system's resilience.
For that reason, Fowell called for recognition of its “broader strategic value,” which includes energy security, regional growth, and a transition pathway for capabilities, companies, and infrastructure historically linked to the North Sea energy industry.
In industrial terms, the potential includes new investments in ports, manufacturing, engineering, underwater operations and maritime services , as well as opportunities for coastal communities that can be incorporated into the next phase of offshore development.
CfD: from the AR5 crisis to the AR7 record
The need to ensure the continuity of the pipeline comes in a market that has experienced significant tensions in recent years. The main British mechanism for attracting renewable energy investment is Contracts for Difference (CfDs) , which provide long-term revenue stability through a strike price .
When the wholesale price falls below the contract value, the project receives the difference; when it rises above it, the project returns the excess. This predictability is especially relevant for offshore wind projects due to the high capital requirements associated with their development and construction.
Allocation Round 5 (AR5) marked a turning point in 2023, when no offshore wind project secured a contract. The maximum prices proved insufficient to offset rising costs for construction, turbines, materials, and financing, forcing the government to revise the economic terms of subsequent rounds.
The recovery became especially visible in Allocation Round 7 (AR7) , the results of which were published in January 2026. The round awarded a record 8.4 GW of offshore wind , between fixed and floating foundation projects, and constituted the largest volume contracted up to that time in a British auction.
The 12 selected projects became a key component of Clean Power 2030. However, the contract award represents only one part of the process and still needs to be translated into construction, connection, and commissioning.
Continue reading
Recent planning documents indicate that, of those 8.4 GW, around 3.2 GW could be generating before the end of 2030 , a difference that exposes the time gap between achieving a CfD and actually supplying electricity to the system.
Market attention now shifts to Allocation Round 8 (AR8) . For offshore wind, the Administrative Strike Price was set at £113/MWh , based on 2024 prices, while floating offshore wind has a maximum of £271/MWh .
The round should show whether the market can sustain the momentum regained in AR7 while pressures on the cost of capital, construction and the supply chain continue.
The CfDs also incorporate an industrial dimension through the Clean Industry Bonus , which allows developers of fixed and floating foundation projects to access additional income in exchange for commitments to more sustainable supply chains.
The goal is for the expansion of offshore wind to increase generation capacity and, at the same time, boost industrial infrastructure, manufacturing capacity and employment within the United Kingdom .
For Regen, these economic incentives must be accompanied by coherent structural signals. Fowell called on the SSEP for a “clear deployment trajectory” that establishes scale, regional distribution, and a development timeline for floating wind power.
Planning will also need to be coordinated with future seabed tenders, network investments, permit reforms, and revenue support mechanisms. Spatial certainty would lose its effectiveness if the rest of the policies do not keep pace with deployment.
The risk increases if the floating developments are pushed beyond the current investment horizon. Fowell warned that such a decision would send a “negative signal” to the market precisely when several projects are progressing from consent to final investment decisions and subsequently to construction.
An interruption in that sequence would also make it difficult to generate economies of scale, sustain suppliers, and accelerate the learning needed to reduce the costs of a technology that is still going through its transition to higher-volume commercial deployment.
The network becomes another bottleneck
The contracted volume needs to grow in parallel with an electrical infrastructure capable of absorbing it. The capacity of the British grid to incorporate new generation became one of the main conditions for meeting Clean Power 2030 targets.
In June 2026, the National Energy System Operator (NESO), along with the network companies, announced that more than 700 projects ready to move forward had received connection offers , unlocking almost 40 GW of additional capacity .
The measure is part of a reform aimed at prioritizing viable and necessary developments to achieve energy goals, gradually replacing the old scheme based mainly on first-come, first-served.
For offshore wind, the expansion of onshore and offshore networks will be especially relevant because a significant part of future generation will be concentrated in areas with abundant wind resources, but far from the main centers of demand.
The UK's performance will therefore depend on the interplay between CfD, permits, access to the seabed, financing, networks, and industrial capacity . A delay in any of these components could affect the overall timeline for the portfolio.
In this scenario, the SSEP goes beyond simply identifying areas for new generation. Planning must coordinate infrastructure and capital decisions around a common long-term strategy that allows technical potential to be transformed into operational parks.
International competition adds pressure to that agenda, as different markets seek to attract technology, manufacturers, expertise, and suppliers linked to floating offshore wind .
Fowell warned that, without a clear British track record, there is a risk that "floating wind technology, expertise and supply chain capabilities" will migrate to countries with stronger commercialization signals.
That move would reduce the UK's industrial and export opportunities in a segment it helped develop and could weaken its own ability to run future parks at competitive costs.
The next five years will thus be a test of British leadership. The country has pipeline, offshore experience, committed capital, and some of the first commercial projects, but it must transform these advantages into installed capacity and a supply chain ready to compete internationally.
AR8 will provide a signal regarding the economic conditions for upcoming developments. The SSEP will have to resolve a broader question: how much floating offshore wind the UK intends to deploy, in which regions, and over what timeframe .
With nearly 14% of the global portfolio and £25.5 billion in commitments associated with ScotWind, the country occupies a relevant position in the industry's takeoff, although that advantage will depend on planning, financing and infrastructure decisions keeping pace with the required speed.
For Fowell, the continuity of the rollout will be the variable that determines whether the United Kingdom manages to reduce costs, consolidate its supply chain and turn its early leadership into a globally competitive industry , in a market where the initial position alone no longer guarantees maintaining the advantage.